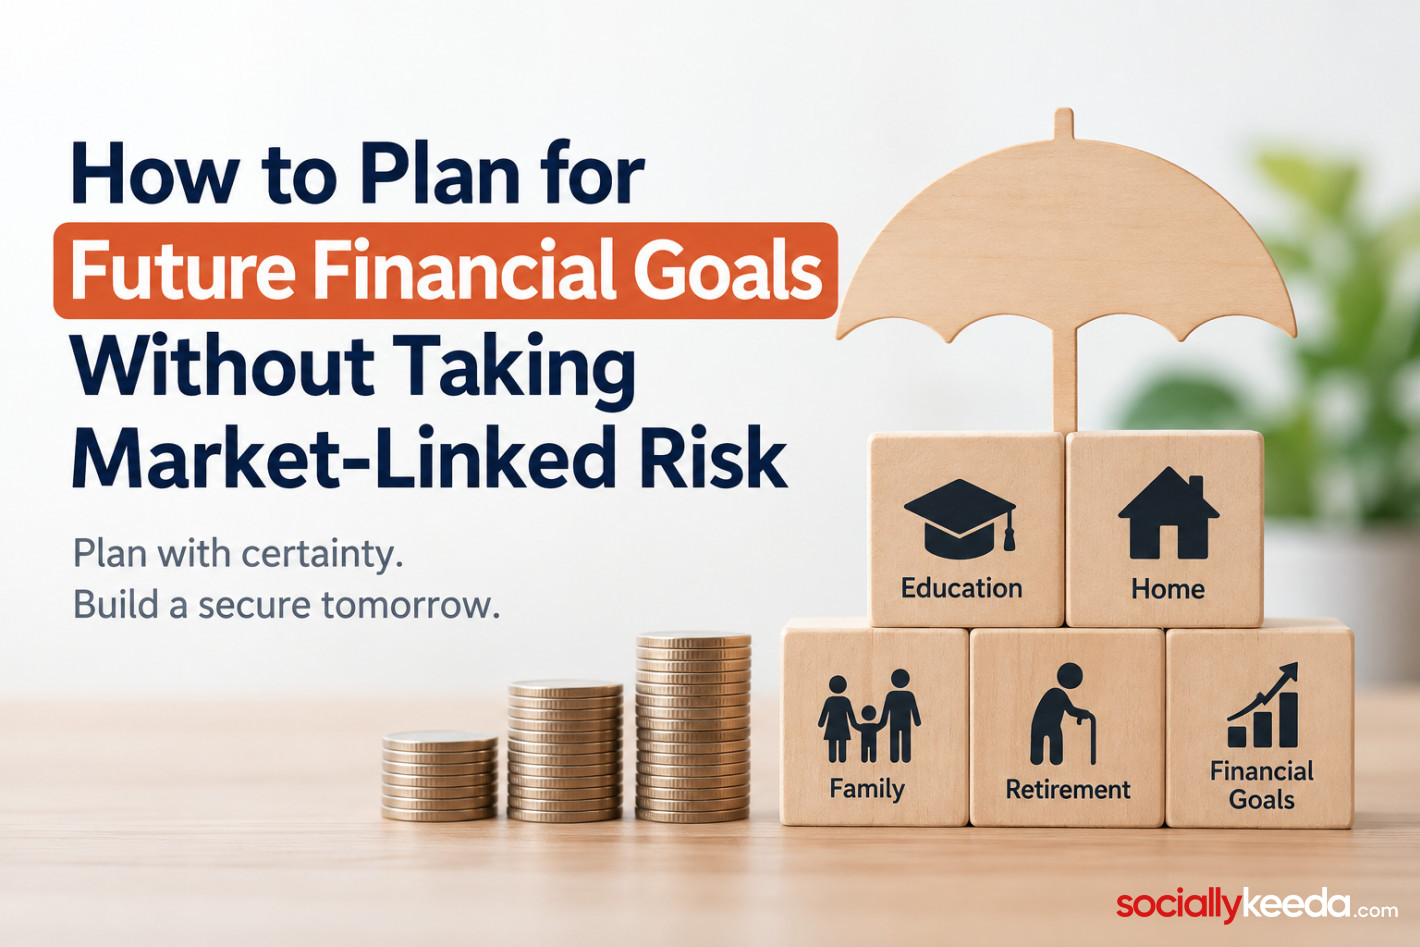
Long-term financial planning often involves balancing two competing priorities: growing money over time and protecting the amount already allocated towards important goals. While market-linked investments can offer growth potential, their returns can fluctuate. For individuals who prioritise greater predictability for specific financial objectives, insurance-based savings products may be worth evaluating.
A capital guarantee plan is designed around this need by combining life insurance protection with a savings component. The structure can provide defined benefits according to the policy terms, while helping individuals work towards planned financial milestones.
Why Capital Protection Can Matter for Goal-Based Planning
Financial goals such as children's education, a future property purchase or building a retirement corpus usually have a defined time horizon. A market downturn close to the goal's target date can affect the value of investments and potentially require the investor to postpone or modify the objective.
A product focused on guaranteed or defined benefits can offer greater predictability, depending on its terms and conditions. This can make such products relevant for individuals who prefer knowing the benefits applicable under specified circumstances when planning for future needs.
However, guaranteed benefits should always be evaluated against the premium payable, policy duration, applicable conditions and the actual benefit structure rather than viewed in isolation.
How a Capital Guarantee Structure Works
A capital guarantee-oriented insurance product generally combines life insurance with savings. The policyholder pays premiums according to the selected payment structure, while the policy provides benefits based on the product's terms.
Read also: Funding Your Parents' Monthly Income: Do Guaranteed Plans Work?
The exact nature of the guarantee can differ between products. Some may specify guaranteed maturity benefits, while others can provide benefits under particular policy conditions. Therefore, prospective policyholders should review the policy illustration and benefit schedule carefully.
It is important to distinguish between guaranteed benefits and non-guaranteed benefits. Any benefit described as non-guaranteed can be subject to factors specified in the policy and should not be treated in the same way as a fixed guaranteed amount.
Where It Can Fit Into a Financial Plan
A guaranteed savings-oriented insurance product may be considered for financial goals where predictability is more important than maximising potential market returns.
For example, someone planning a financial requirement several years ahead could allocate a portion of their financial plan towards a product with defined benefits while using other investments for growth-oriented objectives.
This approach can create different buckets for different purposes:
- Protection for dependants
- Guaranteed or predictable financial goals
- Long-term growth investments
- Emergency savings
- Retirement planning
Separating financial objectives in this way can make it easier to determine which portion of a portfolio should prioritise certainty and which can tolerate market fluctuations.
Capital Guarantee vs Market-Linked Investments
The major distinction lies in how returns and values are determined.
Market-linked investments can fluctuate depending on the performance of the underlying assets. Their value may rise or fall over time, and the final amount available at a particular point can differ from initial expectations.
A capital guarantee solution, where benefits are explicitly guaranteed under the policy terms, focuses more on certainty around specified benefits. This may appeal to individuals who are uncomfortable exposing money earmarked for a specific future requirement to market volatility.
The trade-off is that guaranteed products may not provide the same potential for returns as investments that take higher market risk. Therefore, they should be compared according to the purpose of the money rather than purely on expected returns.
Read also: Best Bond Investment Platforms in India in 2026
Consider the Policy Term Carefully
The duration of the policy is an important factor when assessing any savings-oriented insurance product.
The term should ideally align with the financial goal for which the policy is being considered. A policy intended to support a future education expense, for example, should be evaluated against the approximate timing of that requirement.
The payment period and policy term may not always be identical. Understanding when premiums are payable and when benefits become available is therefore important before making a decision.
Evaluate Liquidity Before Committing
Unlike an ordinary savings account, an insurance policy may not provide unrestricted access to the money throughout its term. Depending on the product, surrender conditions, applicable charges and other policy rules may affect the amount available if the policy is discontinued early.
This makes liquidity an important consideration.
Money that may be required for emergencies should generally not be committed without considering how easily it can be accessed. A separate emergency fund can help prevent the premature discontinuation of a long-term insurance policy.
Life Cover Adds a Protection Element
One distinction between a conventional savings product and an insurance-based savings product is the life cover component.
If the policyholder dies during the policy term, the applicable death benefit can provide financial support to the nominee, subject to the policy conditions. This means the product can serve both a savings-related and protection-related purpose.
Read also: Can a Personal Loan Boost Pay for Your Next Course?
However, individuals should still assess whether the life cover is sufficient for their family's overall protection requirements. A savings-oriented policy may not necessarily replace the need for dedicated term insurance when substantial income protection is required.
Factors to Review Before Purchase
Before selecting a capital guarantee product, examine the complete benefit structure rather than relying only on the guaranteed-return proposition.
Important points include:
- Premium amount and payment frequency
- Policy term and premium payment term
- Guaranteed benefits and their timing
- Non-guaranteed benefits, if any
- Death benefit
- Maturity benefit
- Surrender and withdrawal conditions
- Applicable exclusions
- Tax treatment under prevailing regulations
The policy document and benefit illustration should be reviewed carefully so that the expected outcome is understood before the policy is purchased.
Is a Guaranteed Savings Approach Suitable for Everyone?
A guarantee-focused insurance product may suit individuals who prioritise predictability and are willing to remain invested for the required policy duration. It may be less appropriate for someone who needs high liquidity or is specifically seeking maximum long-term market-linked growth.
The decision should therefore be based on financial objectives, risk tolerance, investment horizon and existing asset allocation.
Making the Decision as Part of a Larger Plan
A capital guarantee plan should not be evaluated independently from the rest of your finances. Consider how much money is already held in savings, investments and insurance, and identify which future goals require greater certainty.
A diversified financial strategy can combine different products for different purposes rather than expecting one product to meet every objective.
Ultimately, the value of a guarantee-oriented insurance product lies in how well its defined benefits fit a specific financial goal. Reviewing the policy term, premium commitment, guaranteed benefits, liquidity restrictions and life cover can help investors determine whether it belongs in their long-term financial plan.
Comments
No comments yet — be the first to share your thoughts.